
CECA Considers Consensus Necessary in the Processing of the Mortgage Law Reform
The reform seeks to promote transparency, reduce litigation, and contribute to legal certainty to preserve the Spanish mortgage model that favors access to housing.
MiFiD II is prompting entities to reconsider their business model regarding marketing and advisory.
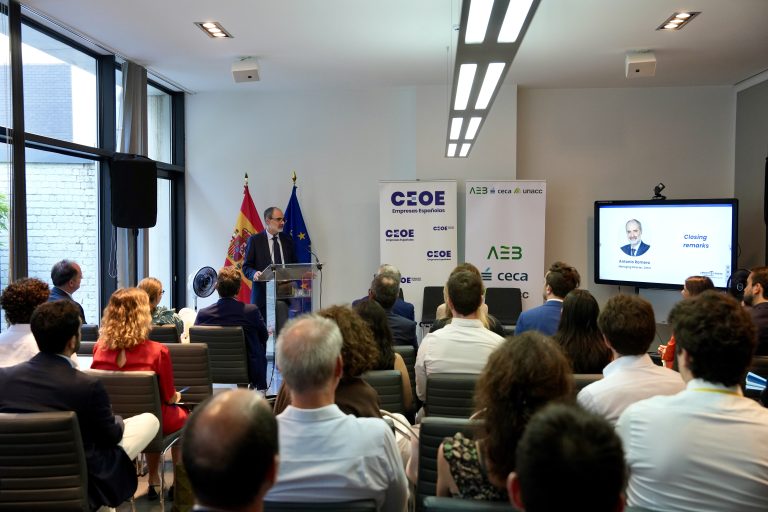
Once again, José María Méndez, General Director of CECA, has participated in the Financial Sector Meeting organized by Deloitte-ABC, which is celebrating its 25th edition today in Madrid under the title “Innovation, Transformation, and Reputation.”
In his speech, the General Director of CECA began by reviewing the macroeconomic environment in which credit institutions operate. He highlighted the growth trend of the Spanish economy recorded over the last four years, although Funcas anticipates a slight slowdown in the last months of 2018, placing the year-end growth rate at 2.8%.
One of the significant imbalances that persist is unemployment, which, with a projected unemployment rate of 15% for 2018, will require retail banking to provision, especially after the implementation of IFRS 9, which is expected to increase the amount of provisions by considering the entire life of the operation.
The Challenge of Profitability
In 2017, there was a widespread improvement in banking profitability in Europe, in the context of greater economic growth worldwide. However, profitability continues to be on the ECB’s agenda as one of the main challenges for the European sector.
According to the latest available data from the European Banking Authority (EBA), as of December 2017, the ROE of banking in Spain stood at 7.0%, maintaining an intermediate position in the European comparison. In the EU as a whole, the ROE stood at 6.1% in December 2017.
Many of the factors that have pressured the margins of banks’ income statements in 2017, keeping profitability – despite its improvement – below the cost of capital, will remain present in 2018. However, a lesser impact is expected on Spanish banking, which will improve its relative position as a result of: the adjustments already made to installed capacity; the efforts made in reducing and cleaning up non-performing assets; and the increasing trend of new credit not only to households but also in productive sectors.
Associative Activity 2018: Regulation
The regulatory pressure has remained constant since the beginning of the crisis and will continue to be present this year 2018.
On the European agenda, the completion of the Banking Union stands out with the approval of the third pillar, the EDIS or European deposit guarantee fund. This is one of the most significant topics on the agenda, which, although much progress has been made on the technical side, has not yielded results due to political issues framed in the debate between countries advocating for advancing “risk sharing” and those that condition it on first addressing the imbalances accumulated during the crisis (the “risk reduction” approach).
Secondly, it is expected that the reduction of doubtful exposures will play a crucial role in this process, which will need to be closely monitored throughout 2018.
Finally, we should not forget the advances in modifying the resolution framework, particularly regarding the development of new MREL policies based on what have been called “transfer strategies,” encompassing measures for business sales or the creation of a bridge bank.
On the national agenda, José María Méndez first highlighted the pending transposition of MiFID II, which is leading entities to reassess their business model concerning the marketing and advisory of investment products. In this regard, Méndez stated: “We will ask that the sale of proprietary products not be stigmatized, as long as the client is advised in a fair and transparent manner.”
Secondly, the processing of the mortgage reform, which aims to promote transparency and contribute to legal certainty in the mortgage market, avoiding the continuous questioning of the clauses used in loan contracts. “Congress should approve legislation that allows broader layers of the population to access home ownership,” said the General Director of CECA.
In conclusion, Méndez wanted to share a final reflection with the attendees: “Facing the challenges that credit institutions present to us allows us to continue contributing to our social function, which is essentially to finance growth and job creation in our country.”