READING MATERIALS OF INTEREST
It is not absurd to say that the most enduring relationship in our lives is probably the one we have with our bank. This statement, perhaps exaggerated for many, contains a good part of truth: there are few services we enjoy for as many years as those provided by our bank.
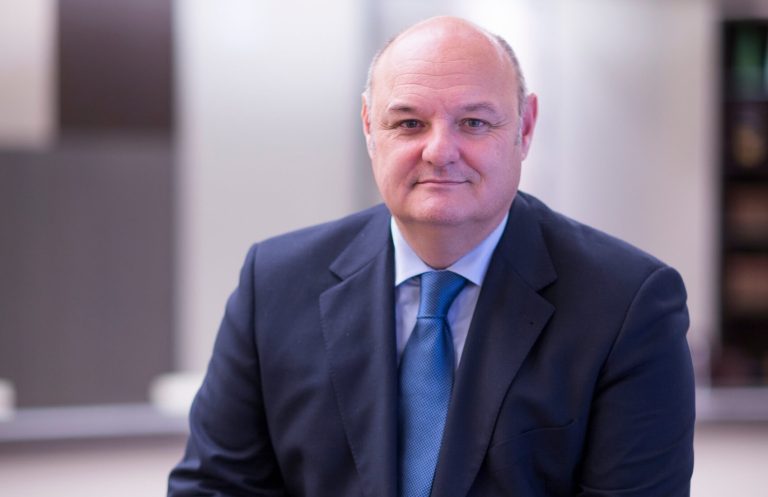
According to Alberto Aza, spokesperson for CECA, the banking association that groups some of the most important entities in our country such as CaixaBank, Kutxabank, Cajasur Banco, Abanca, Unicaja Banco, Ibercaja Banco, Caixa Ontinyent, Colonya Pollença, and Cecabank, “banking services offer opportunities for progress throughout all stages of customers’ lives. This is what sets it apart. A young person just starting their professional life, an adult family with children, or an elderly person wanting to enjoy their retirement comfortably all have different financial needs.”
However, the way we access financial services has transformed significantly in recent years, especially after the pandemic. Banking services were traditionally offered in branches, but as new technologies have advanced, more and more customers prefer to conduct their transactions online or through mobile applications.
According to data from FUNCAS, the think tank dedicated to economic and social research at CECA, 36.4% of Spaniards access their bank daily or almost daily through digital means, which is double the percentage before the pandemic. This hasn’t gone unnoticed by the entities associated with CECA, whose commitment has always been the continuous improvement of the service model offered to their clients.
“We have diversified customer service channels like never before,” states Alberto Aza. “All with the sole purpose of adapting the service to changes in consumption habits and the specific preferences of different customer types. It is clear that some customers prefer to avoid travels and wish to operate with their bank digitally or by phone,” he continues, “but there are others who request in-person service at a branch. There is even another group living in rural areas who need to be attended to through alternative channels that the entities provide.”
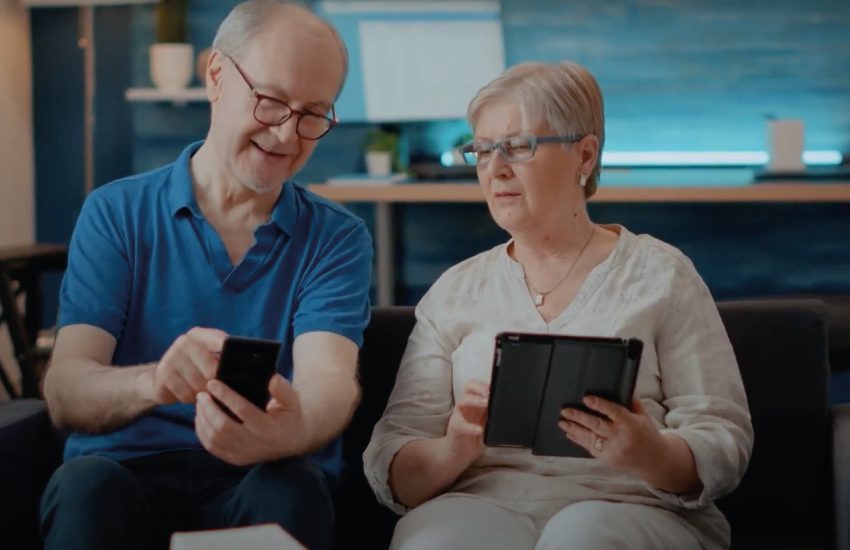
In this adaptation of service delivery depending on the type of client, special attention is required for elderly individuals, who suffer more than others from the impact of the digital divide. “Among the concrete measures we have implemented to address the challenges faced by the elderly are, for example, the extension of cash services, training for branch staff on the specific needs of the group, and preferential service for senior clients,” says Alberto Aza. “We have also taken measures aimed at facilitating the digital interaction of elderly people, for instance, through the adaptation and improvement of the usability of ATMs or digital applications, while also reinforcing digital financial education programs.”
An effort that is bearing fruit, according to surveys: 34.1% of people aged 60 to 70 access their digital banking daily, a figure that surpasses the 18 to 29 age bracket, which only reaches 31%, according to FUNCAS data.
It is no secret that among the most important challenges of banking services is catering to elderly individuals living in isolated rural areas. The entities in the CECA sector have not forgotten them and have created alternative and flexible channels such as mobile offices, popularly known as ofibuses, or financial agents. “More recently,” comments Alberto Aza, “we also have the help of non-banking collaborators, such as post offices or commercial establishments, to ensure our clients’ access to cash.”
In the future, according to CECA’s spokesperson, “banking will continue to move towards a hybrid service model where in-person service will coexist with digital channels. On one hand, offices will be concentrated and reoriented to focus on personalized advice, and on the other hand, digital channels will be strengthened thanks to technological advancements, making them more functional, intuitive, and human.”
Ultimately, the service will continue to adapt to technological changes and customer preferences aiming to be at the forefront, but without renouncing the human and professional quality that has historically characterized banking. “Even though we are heading toward a hyper-digitalized society,” concludes Alberto Aza, “the excellence of banking service will continue to reside in the people who make it possible every day.”
These cookies are essential for the website to function and cannot be disabled. They are generally set in response to actions made by you, such as setting your privacy preferences, logging in or filling in forms.
They enable enhanced functionality and personalisation, such as videos, live chat, preferred language and region.
They allow us to count visits and traffic sources in order to measure and improve the performance of our site. They help us to know which pages are the most and least popular.