READING MATERIALS OF INTEREST
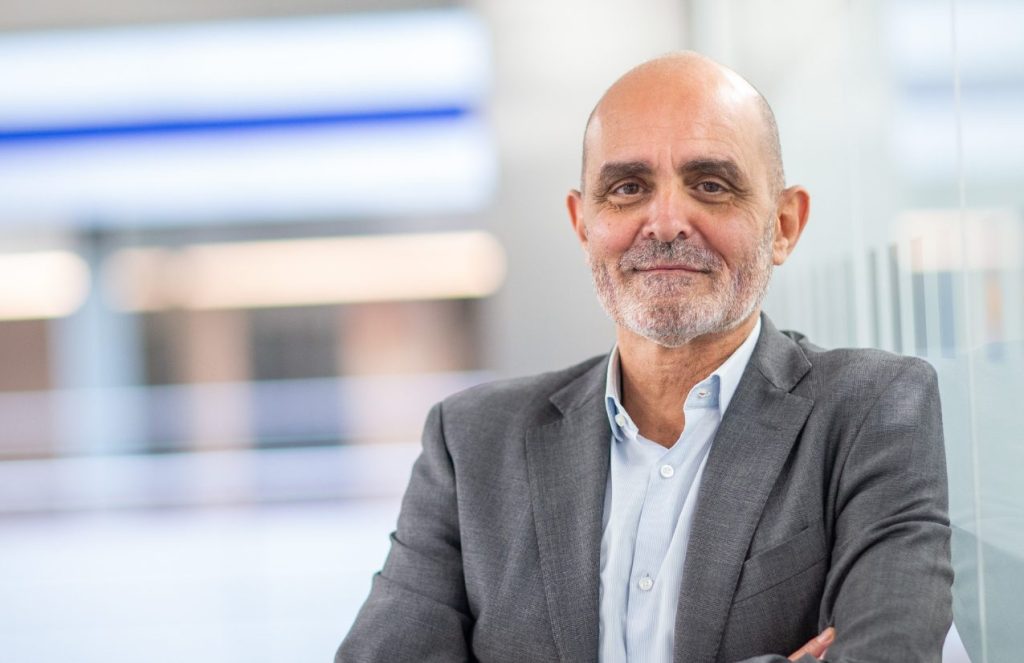
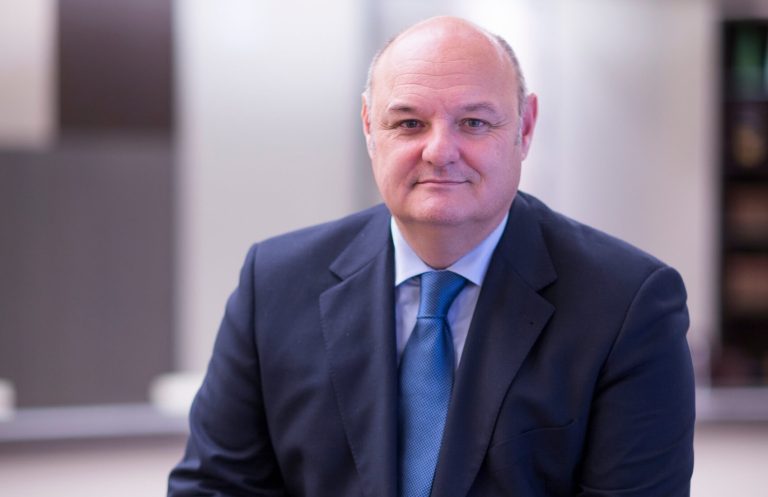
“In villages, there will be shops where customers can withdraw cash” – “Spanish banking is one of the most competitive in Europe and has the lowest fees” – “Job cuts in the sector are being made under better conditions than in others” Alberto Aza, spokesperson for CECA, was in Málaga yesterday for the interview-discourse that CECA’s Ambassador for Social Work and Action, Ona Carbonell, offered at the Unicaja Baloncesto Club facilities in Los Guindos, as part of Unicaja’s Edufinet project. Aza reviews the current state of the financial sector, the controversial processes of office and employment adjustments (Unicaja Banco is currently negotiating a redundancy plan), the competition from fintechs, and the horizon of the Next Generation funds. CECA encompasses credit institutions and banking foundations with nearly €900 billion in assets.
In 2013, the Law on Savings Banks and Banking Foundations restructured the sector by segregating the old savings banks into two entities: on one side, banks, and on the other, foundations to manage the Social Work. Eight years have passed; does the model work?
It has been a successful model that is functioning very well. At that time, the regulatory body was clear that there was that differential element of the old savings banks, the social work, which is why the role of foundations was recognized. With the distribution of dividends, where the foundations are significantly part of the banks’ shareholders, it also ensures this success. The social work continues to be a fundamental activity.
What work does CECA currently perform?
We are a banking association with nearly a century of history (founded in 1928) that represents 40% of the market in Spain. CECA is a fundamental player in the sector, not only because of its experience and trajectory but also because of that social work that is foundational to savings banks. Already in its statutes, it was stated that the purpose was social: accompanying the most disadvantaged. That spirit, which dates back 300 years with the emergence of pawnbrokers, is still relevant today.
The landscape has been very tumultuous in recent years: negative ECB rates, competition from fintechs, and now the pandemic, how has the sector sought to gain profitability?
It is true that there are various conditions (exogenous but with a direct impact on its activity) that mark the pace of banking. The sector’s profitability comes from various vectors. The first is the pursuit of efficiency, which is being achieved through digitalization. This allows for the improvement of internal processes and relationships with customers, who prefer online and mobile channels. On the other hand, there is an awareness that bank branches are becoming less relevant in the relationship between customers and entities. There is little operation in branches. Right now, there is excess installed capacity that will adapt to the new times.
Banking seems to maintain a rising trend in charging fees to customers.
It is another formula for gaining profitability. Banking, like any other sector, provides a series of services that have a cost and an investment. Therefore, it is necessary to charge for them. I will say that Spanish banks obtain 25% of their income from fees, while in countries like France or Germany it goes up to 35%. The average in Europe is over 30%. What I want to say is that the Spanish banking system is one of the most competitive in Europe. Fees are another tool for competition and will be managed cautiously. Each entity will make its decision.
You mentioned the process of closing branches. What happens to all those people in rural areas, many of advanced age, who find themselves without their branch and ATM? Not everyone uses new technologies.
The depopulated Spain represents that 3% of the population that lives in small towns, with older individuals, and where they are indeed being left without offices. What is the banking sector doing? Working on alternative channels, such as mobile offices. At CECA, we already have about twenty of them, and they cover the equivalent of 1.7 times the circumference of the Earth each year through these inland territories. From them, any operation available in a traditional office can be performed, including cash withdrawals. A network of itinerant financial agents is also being deployed, covering a network of more than a thousand Spanish municipalities. Another solution is to resort to non-banking agents (pharmacies, bars, shops) so that locals can withdraw cash. This is already done in the UK or the US, for example, using supermarkets. In Spain, agreements are already being made to do this in Post Office branches. I believe it is important to understand that the phenomenon of depopulation affects all sectors. Banking is in no way responsible.
The elimination of jobs is another controversial topic. We are living in an era of banking layoffs, the latest of which is now at Unicaja after absorbing Liberbank.
The context in which banking operates is difficult, with negative interest rates since 2014, something no one expected, and that, as we have said, affects profitability. Job reductions also respond to the search for greater efficiency. But I want to remind that layoffs in the sector are being conducted in a negotiated manner and possibly under better conditions than in other fields. Moreover, banking personnel is highly qualified, and in many cases, they easily find re-employment.
The European Next Generation funds are coming. What role should banking play?
It should be fundamental. One of the variables considered when making growth predictions is that European funds are executed adequately, meaning they go to viable projects capable of transforming the production fabric in a sustainable manner and that also serve to mobilize private investors. The banking sector has much to contribute here because it knows how to analyze investment projects and their viability, with the possibility of advancing funds and co-financing initiatives. Spanish banking, with its commercial network, has the capacity to channel all this. It was already observed with the ICO credits. Spain was the second country in the EU after France where the most were granted, and that was thanks to the banking office network.
Giants like Amazon and Google have already expressed their interest in providing banking services. Are you concerned about this competition?
We have always said that competition is not only good but also necessary as it is a driver of innovation. These technology companies are collaborating with banking entities or helping to advance the sector. However, we also state that if we compete on the same playing field, we must all adhere to the same rules and regulations, which are among the strictest in Europe. This must be done not only to promote fair competition but also to guarantee consumer protection and the financial stability of the system.
What is your opinion on cryptocurrencies?
Cryptocurrency, like any asset that can be invested in (and in this case, with a strong speculative component), must be properly supervised. And the population must also be aware of what they are getting into. We are concerned that 12% of young people between 18 and 25 years old, according to studies, are already investors in cryptocurrencies, often without due knowledge and taking on excessive risks. This makes them easy prey for financial fraud.
These cookies are essential for the website to function and cannot be disabled. They are generally set in response to actions made by you, such as setting your privacy preferences, logging in or filling in forms.
They enable enhanced functionality and personalisation, such as videos, live chat, preferred language and region.
They allow us to count visits and traffic sources in order to measure and improve the performance of our site. They help us to know which pages are the most and least popular.